Taxation on cross-border electronic commerce
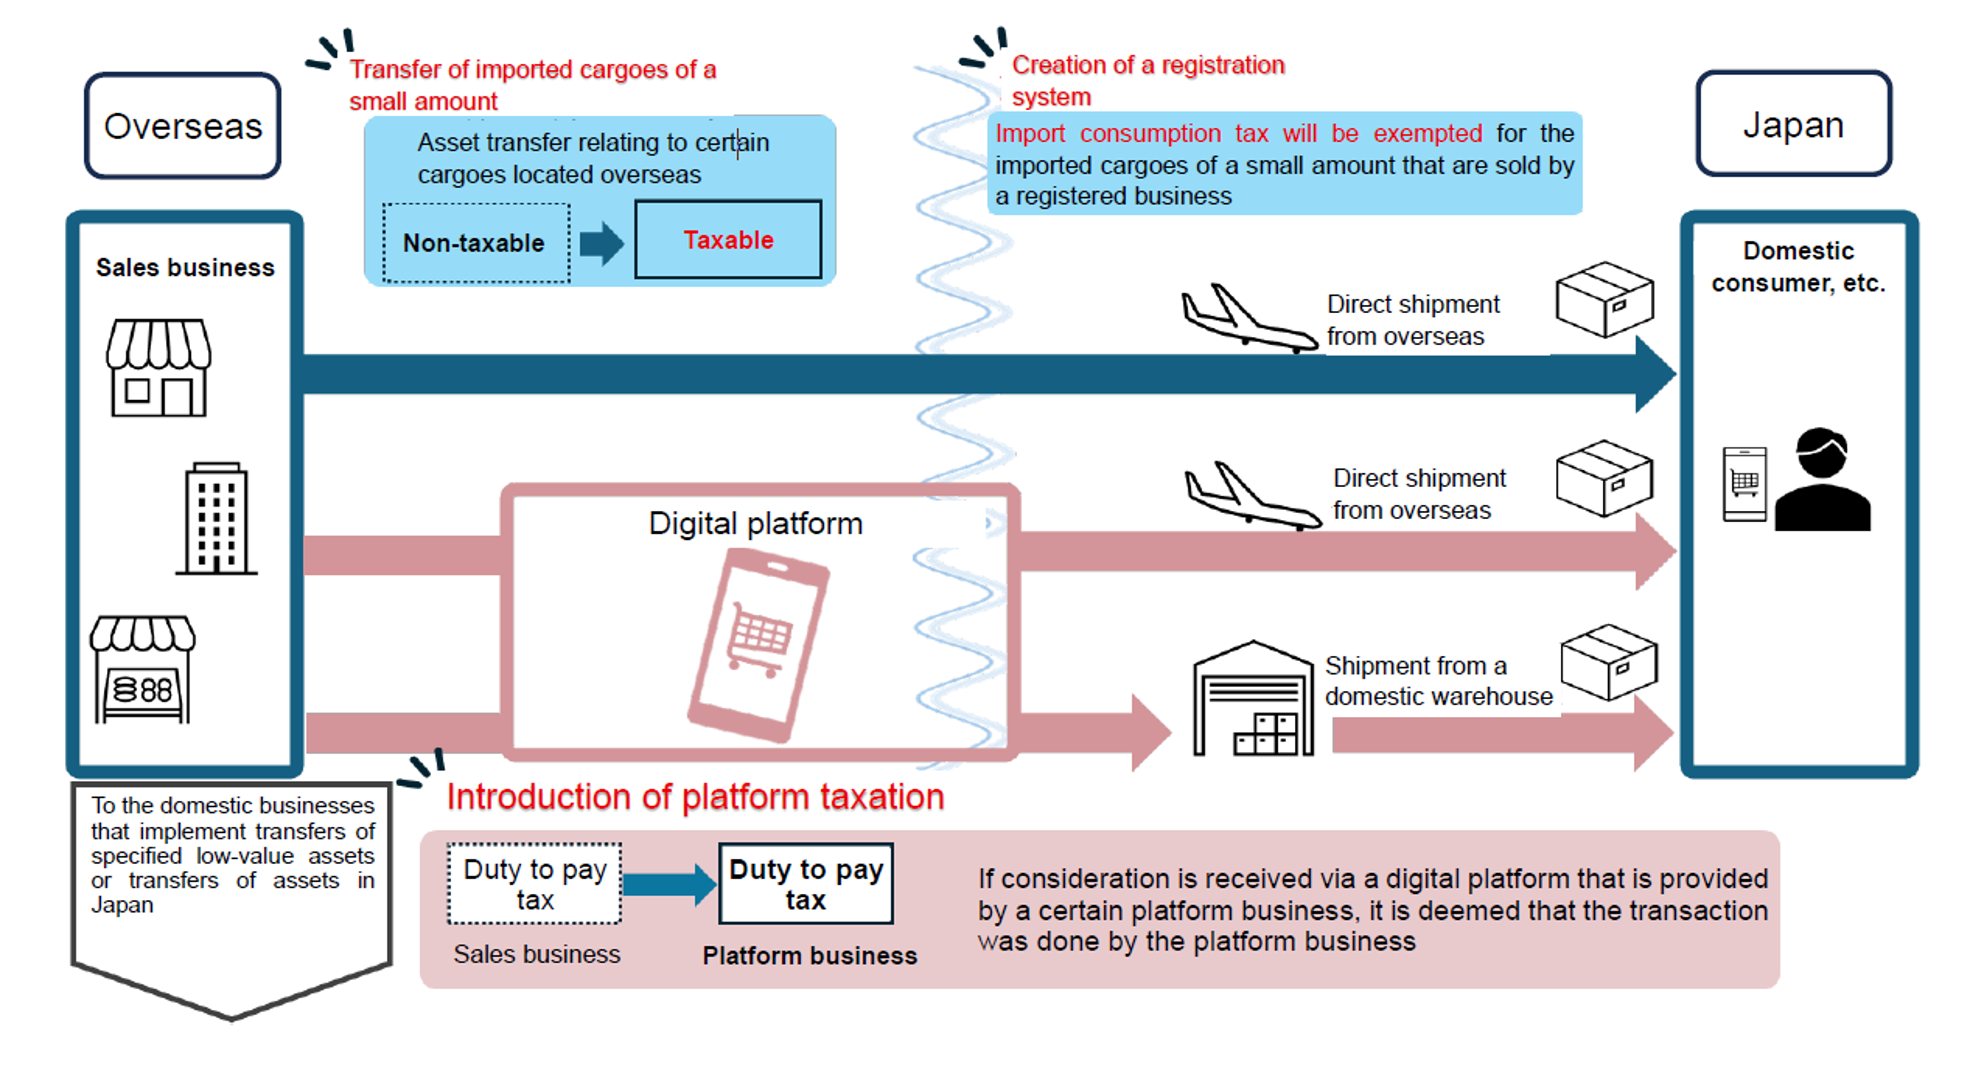
① Revision of the taxation on transfers of imported cargoes of a small amount
From among the asset transfers where each business sends the goods from a location outside Japan to a location in Japan by using the mail order method, those transfers of ¥10,000 or less (excluding tax) in the consideration amount per one asset item (hereinafter “transfers of specified low-value assets”) became taxable for consumption tax, as they are now regarded as asset transfers implemented in Japan, per the revision
② Registration system for registered sellers of specified low-value goods
If a business implements transfers of specified low-value assets or tries to perform so; or if a business uses other entity to receive the taxable goods in relation to the transfers of specified low-value assets from the bonded area, the operator can get registered with the District Director of the competent tax office. After the registration, such business is called a registered seller of specified low-value goods.
From among the cargoes received from the bonded area, if certain taxable goods are proven to have come from the transfers of specified low-value assets carried out by a registered seller of specified low-value goods, consumption tax will be exempted when the goods are received by the importer from the bonded area.
③ About platform taxation
Among the businesses that provide a digital platform such as an online marketplace, certain platform businesses that satisfy specific requirements and are designated by the Commissioner of the NTA are called the designated category 2 platform businesses.
From among certain asset transfers carried out via the digital platform provided by a designated category 2 platform business, in the cases where the consideration amounts are received via the designated category 2 platform business, it is deemed that the designated category 2 platform business did those asset transfers, so it is now set that the operator will need to perform consumption tax declaration and payment (platform taxation).
Overview of the system
Taxation on cross-border electronic commerce
- Taxation on cross-border electronic commerce(July 2026)(PDF/959KB)
- 关于征收越境电子商务税的相关制度(2026年7月)(PDF/1,311KB)
- 關於徵收越境電子商務稅的相關制度(2026年7月)(PDF/1,363KB)
- 국경을 넘는 전자상거래에 관한 과세 관계(2026년 7월)(PDF/1,406KB)
Q&A about Consumption Tax Imposed on Cross-Border Electronic Commerce Transactions
Some of the publications on this site are in PDF. To view them you will need to have Adobe Reader. Please download Acrobat Reader.

